

What the Federal Reserve’s rate hike means for the markets
- 09.18.26
- Markets & Investing
- Commentary
Review the latest Weekly Headings by CIO Larry Adam.
Key takeaways:
- Despite the Fed rate hike, the US economy remains on solid footing
- Fundamentals, not Fed policy, will remain the driver of equity market performance
- Current yields provide an attractive entry point for fixed income investors
As summer officially gives way to fall on September 22, it's not just the weather that's changing. The global monetary policy landscape is shifting as well. After spending much of the past two years focused on supporting growth, central banks have increasingly turned their attention back to inflation, especially with oil prices climbing back above $100 per barrel. While economic activity remains resilient – particularly in the US – interest rates have moved sharply higher as policymakers respond to renewed inflation pressures.
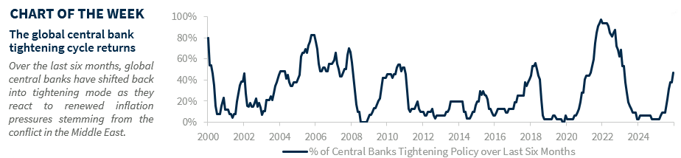
In fact, more than 40% of the 32 central banks we follow have returned to tightening policy over the past six months. The Federal Reserve (Fed) joined that trend this week, delivering a widely anticipated 25 basis point rate hike, its first increase since 2023. For investors, the key question is what comes next. Below, we explore how the Fed's latest decision could shape the policy outlook, the economy and financial markets in the months ahead.
The Fed hikes but signals limited further tightening
After months of internal debate, the Federal Reserve unanimously raised the federal funds rate by 25 basis points to 3.75% to 4.00%, its first increase in three years. Chair Warsh described the move as a step toward “removing a degree of accommodation” based on three key factors: stronger growth, persistent inflation and geopolitical uncertainty.
The updated Summary of Economic Projections reinforced that message, with policymakers modestly raising their growth forecasts to 2.3% in 2026 and 2.4% in 2027, lowering the unemployment rate to 4.1%, and projecting only a gradual return to the 2% inflation target. Importantly, the revised dot plot does not signal a prolonged tightening cycle, showing just one more rate hike this year and steady rates in 2027. In our view, the Fed’s rate hike represents a mid-cycle adjustment rather than a major tightening cycle. As tariff- and energy-related price increases roll out of the year-over-year calculations, the broader disinflation trend should reassert itself, reducing the need for further policy restraint.
What the Fed Rate hike means for the markets
The key question for investors is whether the Fed’s latest move changes the outlook for economic growth, corporate earnings and financial markets. Below, we address the implications for the economy and major asset classes.
Economy
While the Fed meeting dominated the headlines, it may only rank fourth on the list of what's driving the economy today. The more important drivers remain oil prices, the AI-investment boom and the resilience of higher-income consumers. Together, these trends are having a far greater influence on economic growth than a single Fed rate hike. In fact, a 25 basis point increase is unlikely to meaningfully alter any of those three drivers. It's not likely to stop companies from investing in AI, reverse the direction of energy markets – we need a resolution to the Iran war for that – or significantly change spending patterns among higher-income households.
That isn't to say rates don't matter. They do at the margin. But the more meaningful impact is likely to be felt by middle- and lower-income consumers, who are more sensitive to borrowing costs and ongoing affordability pressures, particularly as this year’s tax refund boost fades. For investors, this suggests keeping an eye on the trend in real-time activity metrics rather than being overly focused on the prospect of another rate hike. That said, our 2.3% 2026 GDP forecast remains unchanged from our outlook prior to the Fed’s latest move.
Equities
The first Fed hike has historically led to short-term volatility, not the end of the bull market. Across the six initial Fed hikes since 1990, the S&P 500 fell 3% on average over the next three months. Longer term, returns have been more encouraging, with the S&P 500 gaining approximately 8% on average over the next 12 months and positive more than 80% of the time.
Looking ahead, we believe fundamentals, not Fed policy, will drive market returns. Consensus forecasts call for 15% earnings per share (EPS) growth in 2027, on top of 33% in 2026, while EPS estimates have been revised 17% higher year to date despite higher rates and energy prices, reflecting powerful secular trends such as AI investment.
Corporate America is also less interest-rate sensitive than in past cycles, with just 5% of profits used to service debt today versus approximately 35% in 2000. Strong earnings have also pushed the S&P 500's forward P/E ratio (19.1x) below its 10-year average. While the Fed's hike could create near-term volatility, we do not believe it changes the broader investment story. As long as economic and earnings growth remain positive, investors should stay focused on fundamentals rather than the hike itself. We maintain our June 2027 S&P 500 target of 8,200.
Fixed income
Treasury yields are up sharply as the market reassessed the Fed’s rate path amid the renewed surge in oil prices, pushing the 10-year yield above 5% for the first time since 2007. As the Fed shifts toward a higher-for-longer rate environment, Treasury yields will likely require easing geopolitical tensions and lower energy prices to decline meaningfully in the near term. But with bearish sentiment reaching an extreme and the fed funds futures market priced for a 4.6% terminal rate, a full 50 basis points above the Fed’s projected rate path, further upward pressure on rates is likely to be limited.
While yields remain above our 4.25% to 4.50% June 2027 forecast, we think today’s levels offer one of the more attractive entry points for investors in recent years, providing compelling income and attractive capital appreciation potential should growth concerns reemerge.
All expressions of opinion reflect the judgment of the author(s) and the Investment Strategy Committee and are subject to change. This information should not be construed as a recommendation. The foregoing content is subject to change at any time without notice. Content provided herein is for informational purposes only. There is no guarantee that these statements, opinions or forecasts provided herein will prove to be correct. Past performance is not a guarantee of future results. Indices and peer groups are not available for direct investment. Any investor who attempts to mimic the performance of an index or peer group would incur fees and expenses that would reduce returns. No investment strategy can guarantee success.
Economic and market conditions are subject to change. Investing involves risks including the possible loss of capital.
The information has been obtained from sources considered to be reliable, but we do not guarantee that the foregoing material is accurate or complete. Diversification and asset allocation do not ensure a profit or protect against a loss.
The S&P 500 Total Return Index: The index is widely regarded as the best single gauge of large-cap U.S. equities. There is over USD 7.8 trillion benchmarked to the index, with index assets comprising approximately USD 2.2 trillion of this total. The index includes 500 leading companies and captures approximately 80% coverage of available market capitalization.
Sector investments are companies focused on a specific economic sector and are presented here for illustrative purposes only. Sectors, including technology, are subject to varying levels of competition, economic sensitivity, and political and regulatory risks. Investing in any individual sector involves limited diversification.
